It’s April: Time to Explore Potential Tax Savings

Even though our weather hasn’t changed, the calendar shows that it is April. April brings the NCAA Tournament, the start of the baseball season and the start of the Stanley Cup playoffs. April 15th is also the date taxes are due.

Taxes can include capital gains generated by the sale of real property. Looking for a way to limit your exposure – think about entering into a tax free exchange permitted under Section 1031 of the Internal Revenue Code. Recently, we helped clients through this exchange process enabling them to avoid significant capital gains.

The tax free exchange is particularly attractive to property owners whose property has substantially increased in value and who are facing the payment of substantial capital gains.

The tax free exchange process involves the cooperation of the Seller and Purchaser and the use of a third party exchange company. Section 1031 provides a seller with 45 days after the date of closing to identify possible exchange properties and an additional 135 days to close on a property.
Big-Box Retail Stores, Shopping Centers & Other Transfer Act Land Mines for Connecticut Developers, Owners & Lenders

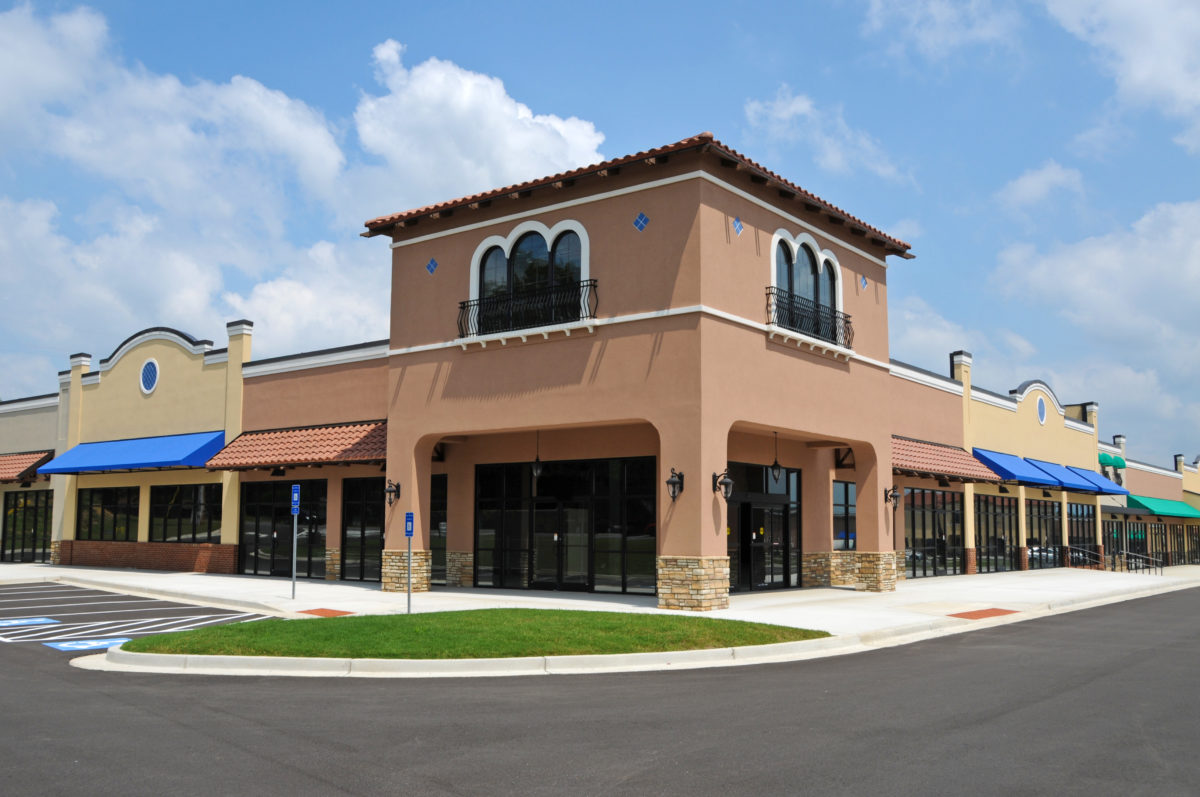
Be careful because you may just get what you wished for. Big-box retailers, home improvement stores, grocery stores, and pharmacies are certainly desirable tenants. However, from a Transfer Act perspective, these seemingly innocuous enterprises often generate significant quantities of hazardous waste.

For example, take some stale or obsolete inventory (nail polish, pesticides, bleach), add returns that are discarded as waste, and finish it off with a dash of spent cleaning products previously used to maintain the appearance of the store. And like magic, you have created an establishment now subject to the Connecticut Property Transfer Act program! As seriously, both the owner and the retail tenant may also be storing and/or disposing of its waste in violation of state and federal environmental hazardous waste laws.

What is the solution?

First, leases must be drafted to assure that tenants do not generate sufficient quantities of hazardous waste to trigger the applicability of the Transfer Act. Leases must also include language assuring that tenants will comply with all federal and state environmental hazardous waste laws.

Second, tenants must understand the need to review their possible waste streams to avoid generating 100 kg of hazardous waste in any month.

Third, even if the Transfer Act avoidance is not practical, owners must assure that tenant operations are conducted in a manner that will minimize releases to the environment.

In summary, the importance of this commentary is to highlight the possible impact of large retail operations on Transfer Act applicability. These operations often fly below the radar, not raising any obvious warning signs. It should now be clear that the environmental aspects of these operations must be managed to assure that the owner-tenant relationship remains successful.